Credit Is a Game You Need to Understand Before You Start Playing—What to Do, What NOT to Do, and How to Build Your Score

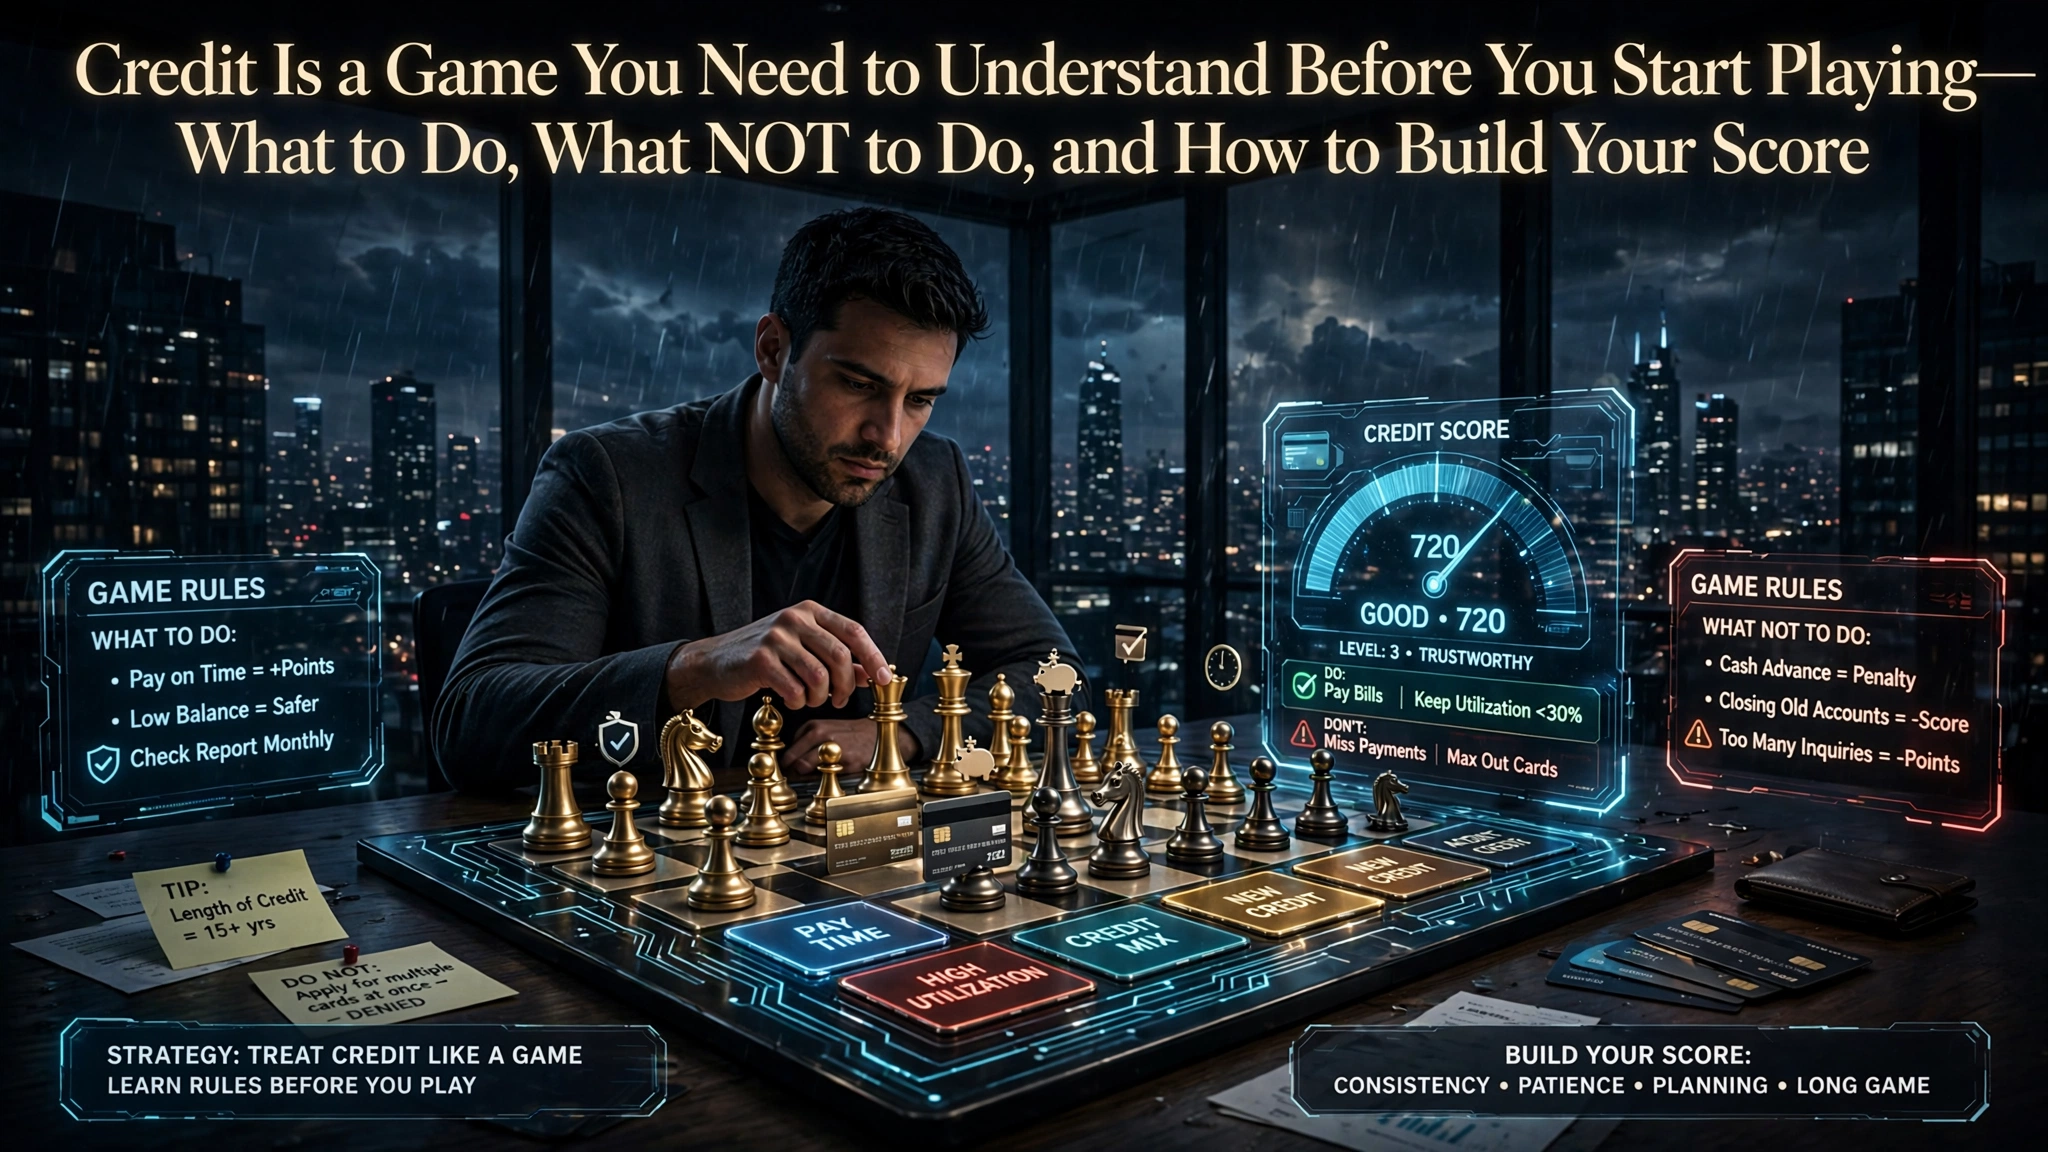
Nobody really sits you down and explains how credit works. You get handed a credit card, somebody offers you a car loan, and before you know it, you're making payments on money you already spent. Then one day you need an apartment, a vehicle, or a mortgage, and suddenly a three-digit number has something to say about your financial opportunities. Let's talk about credit before you learn everything the expensive way.
Credit is one of those financial subjects that can either work in your favor or become a long-term headache depending on how you manage it.
And here's the first thing everybody needs to understand: building credit is not the same thing as building wealth.
You can have an excellent credit score and still have very little money in your bank account. You can also have money saved and a relatively low credit score because you haven't established much borrowing history.
Credit measures how you have managed borrowed money. It doesn't measure your character, intelligence, work ethic, or how much money you have saved.
So let's break down what you should do, what you should avoid, and how to stop making decisions that can hurt your financial future.
WHAT YOU SHOULD DO
1. Pay every account on time.
This is the foundation. Payment history is the largest factor in many commonly used credit scoring models. With FICO, it accounts for approximately 35% of your score.
Set up automatic payments for at least the minimum due if you can safely maintain enough money in the account. You can always make additional payments manually.
Don't rely on remembering every due date. Life gets busy, and forgetting a payment can become an expensive mistake.
2. Keep your credit utilization low.
Credit utilization is how much of your available revolving credit you're using.
For example, if your credit card limit is $1,000 and your reported balance is $300, you're using 30% of your available credit.
A commonly recommended target is below 30%, with lower utilization often being better for your score. People with the highest scores frequently maintain utilization below 10%.
But don't get confused: you do not need to carry a balance and pay interest to build credit.
You can use your credit card, pay the statement balance in full by the due date, and avoid interest on purchases when your account has a grace period and you meet its terms.
3. Start with manageable credit products.
If you're new to credit, consider a secured credit card or a legitimate credit-building product that reports payments to the major credit bureaus.
You don't need a $10,000 credit limit to prove you can manage credit responsibly.
Start small. Make purchases you could already afford with cash. Pay them off responsibly. Build a history over time.
4. Keep older accounts in good standing.
Length of credit history matters. An older account can contribute valuable history to your credit profile.
Don't automatically close an account just because you aren't using it. Consider annual fees, account terms, security, and how closing it could affect your available credit before making that decision.
5. Check all three credit reports.
Equifax, Experian, and TransUnion maintain separate credit files. Information can differ between them.
Check for accounts you don't recognize, incorrect balances, inaccurate late payments, duplicate collections, and information that should have been updated.
You can access free weekly reports through AnnualCreditReport.com.
6. Build savings alongside your credit.
This might be the most important financial lesson in the entire article.
Don't spend your entire paycheck paying credit cards just to maintain a good score while having absolutely nothing saved for emergencies.
Credit is a financial tool. Savings are your safety net.
Having money available when your car breaks down, your hours get reduced, or an unexpected expense arrives can prevent you from relying on expensive debt.
WHAT YOU SHOULD NOT DO
1. Don't max out your credit cards.
Just because a bank gives you a $5,000 limit doesn't mean you should spend $5,000.
That available credit isn't extra income. It's borrowed money that comes with repayment obligations.
Using nearly all your available credit can hurt your score, increase your financial pressure, and leave you with less room to handle emergencies.
2. Don't apply for every credit card offer you receive.
Retail stores love offering discounts when you open a new credit account. You might save 15% on a purchase, but that doesn't automatically make opening another account a smart financial decision.
Multiple applications in a short period can generate hard inquiries and make lenders question why you're seeking so much new credit.
Apply when there's a legitimate reason, not because somebody offered you a discount at the register.
3. Don't carry debt just to build credit.
This is one of the biggest misconceptions.
You do not have to pay interest every month to prove you're responsible. Carrying a balance doesn't earn you bonus points for being a loyal customer.
If you can pay your statement balance in full, do it.
The credit card company might prefer collecting interest, but your financial goal should be keeping as much of your money as possible.
4. Don't ignore bills just because they're not credit cards.
Not every monthly bill automatically reports to the credit bureaus, but unpaid obligations can sometimes be sent to collections or otherwise affect your credit history.
Understand which accounts report, what happens when payments are missed, and what your agreements actually say.
5. Don't believe companies promising overnight credit repair.
There are legitimate credit counseling organizations and professionals who can help you understand your reports, but be careful with companies promising to erase accurate negative information or guarantee a particular score.
Accurate negative information generally cannot simply be removed because you paid somebody to challenge it.
You have the right to dispute inaccurate information yourself for free.
6. Don't co-sign loans without understanding the consequences.
When you co-sign, you're not just doing somebody a favor. You're accepting legal responsibility for that debt.
If the other person stops paying, the lender can pursue you. Late payments can affect your credit, and the debt may affect your ability to qualify for other financing.
Never co-sign something you aren't financially prepared to repay yourself.
UNDERSTANDING WHAT MAKES UP YOUR CREDIT SCORE
For a typical FICO scoring model, the approximate breakdown is:
Payment history: 35%
Amounts owed: 30%
Length of credit history: 15%
New credit: 10%
Credit mix: 10%
These percentages are general guidelines, not a guaranteed formula for every person's score. Different scoring models and lenders can evaluate credit information differently.
And don't go opening a mortgage, car loan, and three credit cards just to diversify your credit mix. You don't need every type of account to build a good score.
THE CREDIT HABITS THAT CAN CHANGE YOUR FINANCIAL FUTURE
Here's a simple approach:
Start with one manageable account. Use it for something you already budgeted for. Pay on time. Keep the reported balance low. Monitor your reports. Build savings. Avoid unnecessary applications.
Repeat that process consistently.
Credit building is a long-term process. There isn't a magic purchase that suddenly transforms your financial profile.
And remember, your credit score can fluctuate. A temporary drop doesn't mean you've ruined everything. Understand what changed before making another financial decision.
THE BIGGER PICTURE
I think one of the biggest mistakes people make is treating credit like money they actually own.
A $10,000 credit limit doesn't mean you're $10,000 richer. An approval for a $40,000 vehicle doesn't mean you can comfortably afford that vehicle. And a high credit score doesn't mean you should take on more debt.
Don't build a financial lifestyle around how much somebody is willing to lend you.
Build it around how much you can actually afford, how much you can save, and how much financial freedom you want to have.
Learn how credit works before you need it. Protect the history you're building. Don't pay unnecessary interest just to impress a scoring model.
The goal isn't to become somebody who can borrow a lot of money. The goal is to become somebody who doesn't have to borrow money every time life happens.




Comments
No comments yet, be the first submit yours below.