Robbing Peter to Pay Paul: I'm Tired of Being Peter!

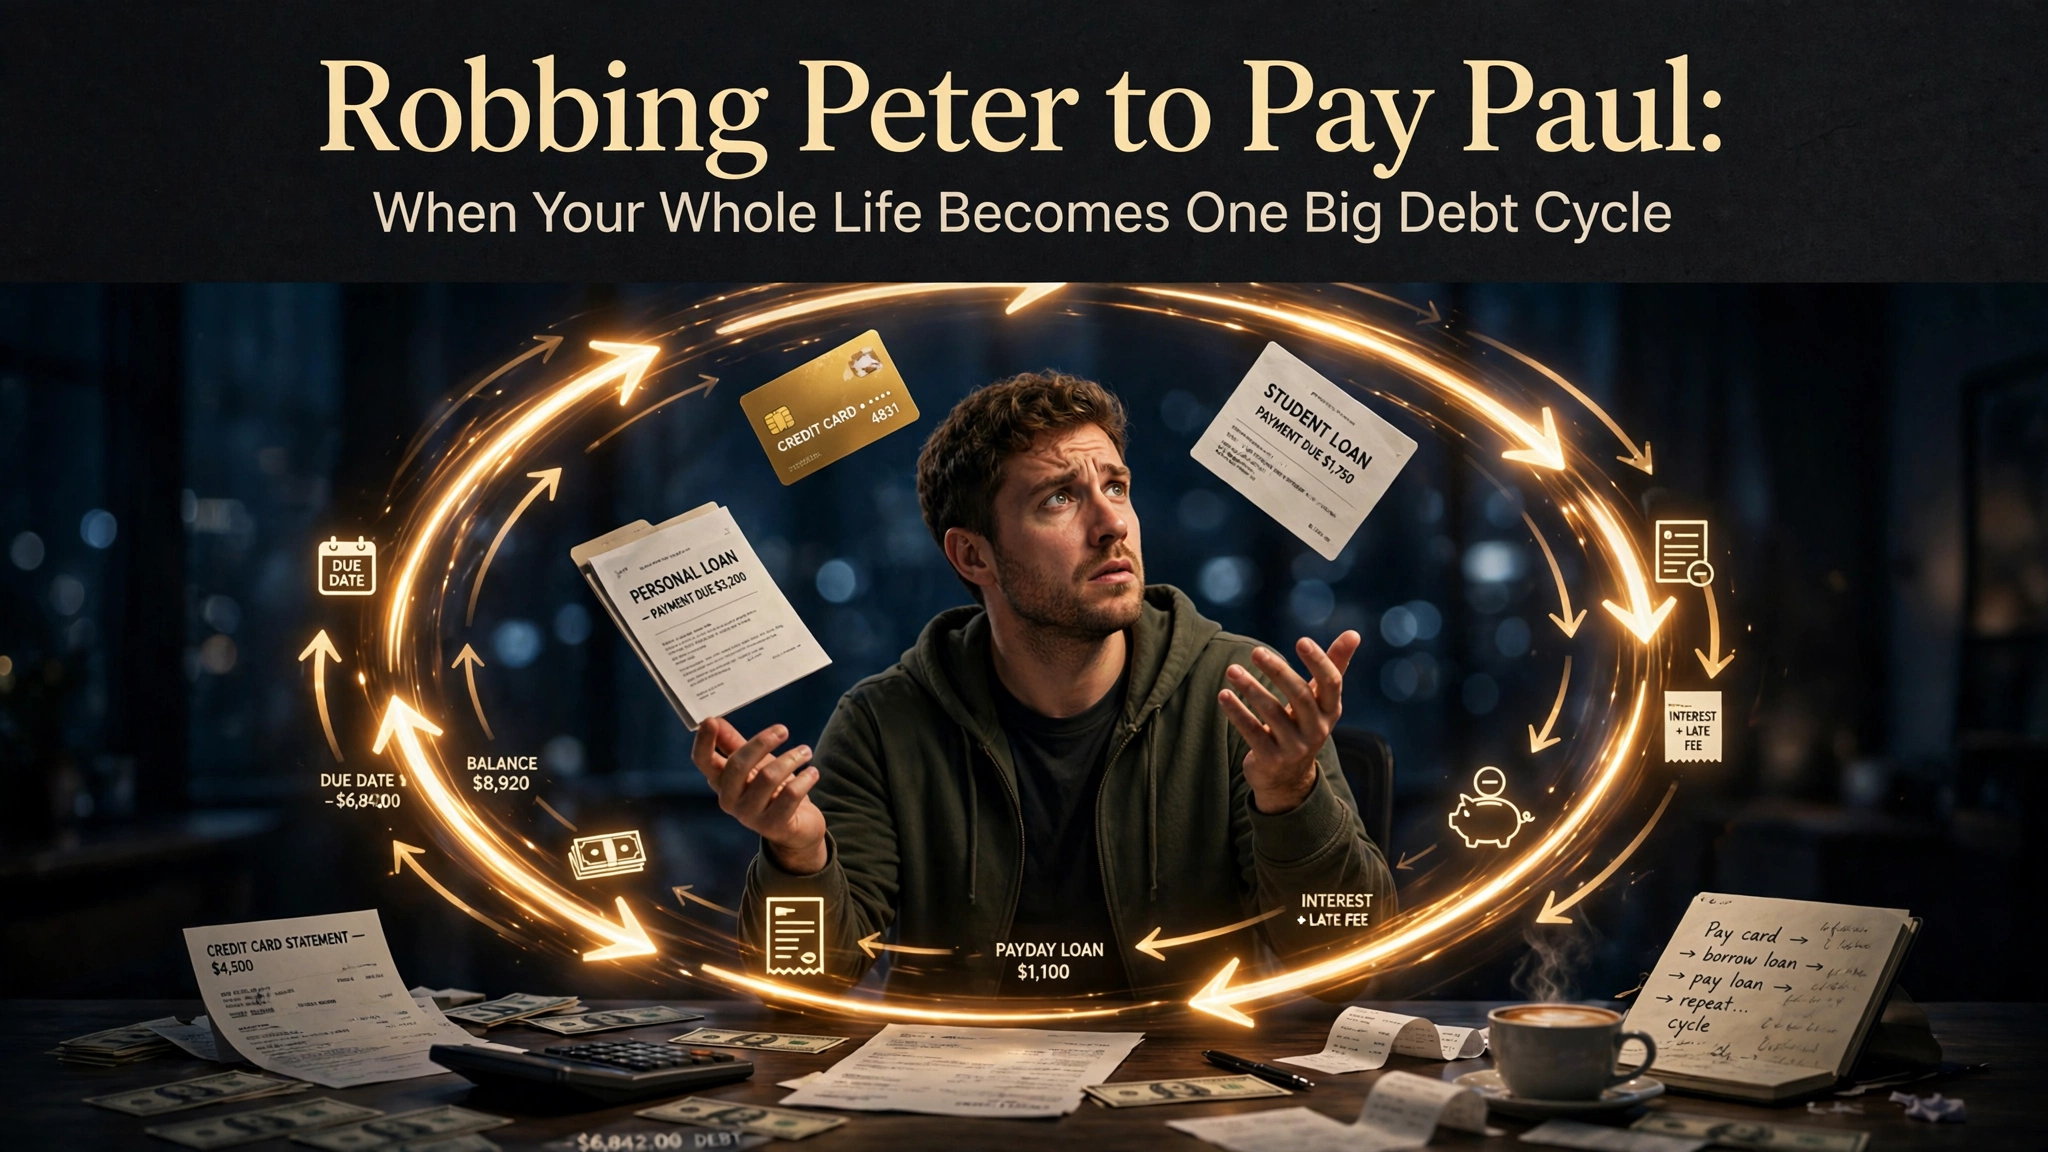
I'm tired of robbing Peter to pay Paul. And honestly? I HATE BEING PETER! 😂 Every time somebody needs money, every time a bill comes up, every time life throws another expense at me, somehow I'm the one getting robbed! My paycheck comes in, everybody gets their cut, and I'm sitting there looking at my bank account like, "Damn, can I get robbed a little less this month?"
Let's talk about living in debt, because a lot of people aren't actually getting ahead financially. They're just moving money around, trying to keep their heads above water. You get paid on Friday, pay the bill that's been waiting all week, and suddenly you're short on the next bill. So now you borrow from somebody, swipe a credit card, or push another payment back just to make everything work.
You're not fixing the problem. You're just changing who you owe money to.
And the funniest part is that people call this managing your finances. No, this is financial gymnastics! You're flipping money from one obligation to another, hoping you stick the landing before the next late fee shows up.
Peter is exhausted, Paul is impatient, and apparently I'm the only fool funding the entire operation!
Every payday feels like you're hosting a giveaway you never agreed to sponsor. The landlord gets paid. The electric company gets paid. The phone company gets paid. The insurance company gets paid. The credit card company gets paid. Everybody is celebrating except you, because after all that money leaves your account, you're wondering whether you can afford to eat something that didn't come from the dollar menu.
And don't get me started on unexpected expenses. Your car needs a repair, and now you're behind on rent. Your child needs something for school, and now the credit card balance goes up. The electric bill is higher than expected, and suddenly you're rearranging your entire financial life like you're solving a Rubik's Cube with a blindfold on.
One unexpected expense can throw the entire month into chaos when there's no savings to fall back on. That's how people end up paying interest on emergencies that happened months ago while trying to survive the emergencies happening today.
You're working for today's money, but yesterday's problems already have dibs on tomorrow's paycheck.
And what makes this situation even more frustrating is that you're often trying to do the right thing. You're working. You're paying bills. You're trying to take care of your responsibilities. But when your income barely covers your essential expenses, there's very little room for mistakes, emergencies, or even a little enjoyment.
People love giving financial advice, too. "Stop buying coffee." "Stop eating out." "You need to budget better." And yes, spending habits matter. Sometimes cutting unnecessary expenses can make a real difference. But let's stop acting like everybody can solve their financial problems by skipping a $5 coffee.
If your rent, groceries, transportation, insurance, utilities, and childcare are consuming nearly every dollar you earn, the math may be the problem. You cannot budget money that simply isn't there. Sometimes people need higher income, lower major expenses, better debt terms, or a combination of all three.
And the people who borrow money aren't always borrowing because they want the latest designer shoes or a luxury vacation. Sometimes they're borrowing because the car needs to run so they can get to work. Sometimes it's groceries. Sometimes it's keeping the lights on.
That's what makes the debt cycle so dangerous. Borrowing can solve an immediate problem, but the repayment takes money away from the next paycheck. Then the next paycheck comes up short, and the borrowing starts all over again.
Eventually, you're not just trying to pay your bills. You're trying to pay your bills while paying for the money you borrowed to pay your previous bills.
Read that again. You're paying money to access money you needed because your money was already gone.
And somewhere in this whole financial circus, I'm still Peter. 😂
Everybody talks about Paul getting paid, but what about Peter? Does Peter ever get a vacation? Does Peter ever get to put money in savings? Can Peter buy something nice without calculating how it's going to affect three other bills?
No! Peter is always getting robbed, and at this point, Peter needs a lawyer!
But jokes aside, constantly living this way can wear you down mentally. You stop thinking about building wealth because you're too busy thinking about making it to Friday. You stop planning vacations because you're planning payment dates. Saving feels impossible, investing feels out of reach, and every little financial victory seems to disappear the moment another expense shows up.
Eventually, you can start believing that this is simply how life works. Get paid, pay everybody, borrow what you need, and repeat until retirement. But just because a financial cycle has become normal doesn't mean it's healthy or sustainable.
The first step toward breaking it is figuring out where the cycle starts. Look at your essential expenses, debt balances, interest rates, and payment dates. Identify which obligations keep forcing you to borrow again. If you can't cover basic necessities and minimum payments, contact creditors to ask about hardship options or payment arrangements. A reputable nonprofit credit counselor may also help you explore a workable plan.
Paying down the highest-interest debt can reduce what you pay over time, while eliminating a smaller balance first can give you a psychological win. The right approach depends on your circumstances. And if the budget simply doesn't cover your necessities, stabilizing your situation has to come before pretending you can aggressively pay off every debt overnight.
The goal is to reach a point where your paycheck belongs to your present and your future, instead of being completely consumed by your past. A point where an unexpected expense doesn't automatically require a loan. A point where payday actually feels like payday.
Because I'm tired of being Peter. I want to be the person who finally gets to keep some money! 😂
I don't want every dollar I earn to have somebody else's name written on it before it even hits my account. I want to pay my responsibilities, build my savings, take care of my family, and enjoy some of the money I work so hard to make.
That's not asking for a mansion or a private jet. That's asking for a little financial breathing room.
So if you're out here robbing Peter to pay Paul, just know you're not alone. But eventually, something has to change. Whether that's the spending, the debt structure, the income, or the cost of the life you're trying to maintain, the cycle has to be addressed if you want a different outcome.
And if you're the person everybody keeps borrowing from, covering for, or expecting to come through financially, remember this: helping people is one thing, but destroying your own financial stability to keep everybody else afloat is another.
Let's debate this: Are people robbing Peter to pay Paul because they're living beyond their means, or because the cost of simply living has gotten so expensive that even responsible people are struggling to keep up? And most importantly, who's tired of being Peter? 😂




Comments
No comments yet, be the first submit yours below.