As an Adult, You Need Three Financial Accounts—One to Collect Money, One to Build Wealth, and One to Manage Credit

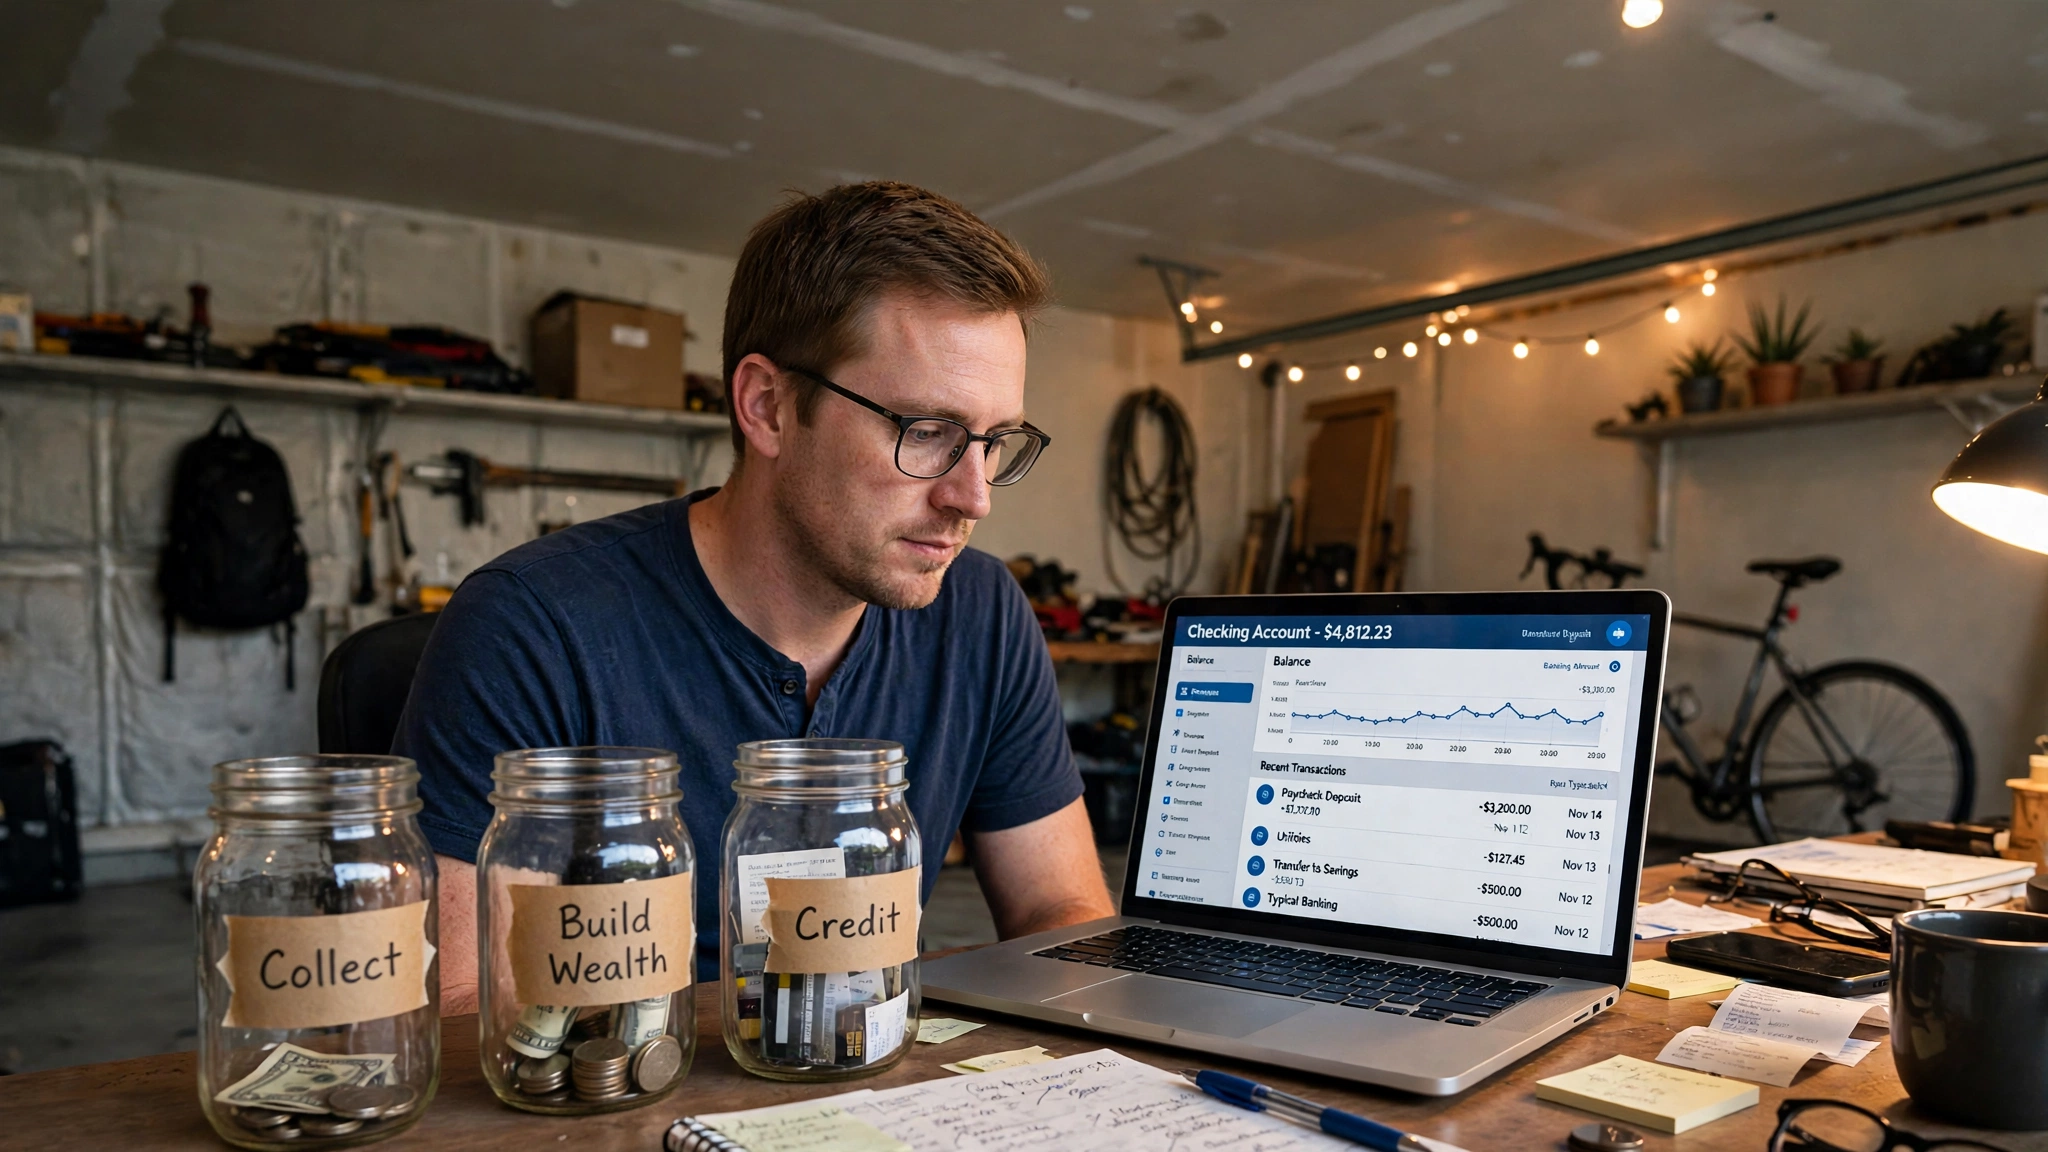
One of the biggest financial mistakes you can make as an adult is putting all your money in one account and treating your entire balance like it's available to spend. Your paycheck comes in, your bills go out, you buy a few things, and suddenly you're wondering where all your money went. What if you stopped treating your money like one big pile and started giving every dollar a specific job?
As an adult, you need a financial system. Not necessarily something complicated, but something that separates the money you're accumulating, the money you're building wealth with, and the credit you're using.
A simple way to think about it is three accounts: an income and distribution account, an investment account, and a credit account.
Account #1: Your Money Collection and Distribution Account
This is where your income lands. Whether you're receiving a paycheck, business revenue, gig-work earnings, or money from multiple sources, this is your central financial account.
But here's the important part: You don't treat the entire balance like spending money.
You use this account to organize and distribute your money. Once income comes in, you decide how much goes toward living expenses, how much gets transferred into investments, and how much goes toward paying down your credit balances.
Think of this account as the control center for your finances.
For example, imagine you bring in $1,000. Instead of looking at that $1,000 and thinking you have a thousand dollars to spend, you assign it responsibilities.
- Living expenses and upcoming bills.
- Money transferred into savings or investments.
- Payments toward credit card balances.
- An emergency cushion for unexpected expenses.
The amounts will depend on your income and obligations. The principle is that money gets assigned before it gets spent.
Account #2: Your Investment and Wealth-Building Account
This is where you put money that has a long-term purpose.
Instead of leaving every dollar in the same account you use for groceries, gas, and entertainment, you move money into an account dedicated to building your financial future.
Depending on your goals, this could include:
- A high-yield savings account for your emergency fund and short-term goals.
- A retirement account such as an IRA or employer-sponsored 401(k).
- A brokerage account for investments such as stocks, bonds, or diversified funds.
These accounts serve different purposes, so don't confuse your emergency savings with money you're investing in the stock market. Money you may need immediately shouldn't be exposed to investment-market volatility.
The idea is to create separation. When you see money in your investment account, you recognize that it has a different purpose. It's not there to finance an impulse purchase or cover a weekend of entertainment.
You're building something that can potentially grow beyond the money you personally contribute.
Account #3: Your Credit Account
This is where things get interesting because credit is something many adults use without actually understanding how to manage it.
Your credit account should be treated as a financial tool, not an extension of your income.
A credit card can help you establish payment history, manage purchases, and potentially earn rewards. But the balance still represents money you owe.
Here's the rule: If you use a credit card for a purchase, your income account should already have the money available to pay for that purchase.
For example, if you spend $100 on groceries using your credit card, that $100 should already be accounted for in your budget. When the statement arrives, you can pay the statement balance in full rather than carrying debt and paying interest.
You don't need to carry a balance or pay interest to build good credit. Payment history, credit utilization, account age, and other factors can influence your credit profile.
Think of credit as a tool you manage, not money you actually own.
Why Separating Your Money Changes Everything
When everything sits in one account, it's easy to confuse your available balance with your actual financial position.
You might have $4,000 in checking, but $2,500 is already committed to bills, $500 is supposed to go toward savings, and another $300 is reserved for a credit card payment.
Technically, you see $4,000. Realistically, you have much less available to spend.
Separating your financial responsibilities makes those decisions easier. You can see what you're accumulating, what you're investing, and what you owe.
Give Every Dollar a Destination
You don't have to be wealthy to organize your finances. You don't need thousands of dollars to start investing, and you don't need multiple complicated financial products to begin managing money responsibly.
You need a plan that works with the income you actually have.
Start by separating your everyday spending from your savings goals. Build an emergency cushion. Make consistent contributions toward long-term investments when your essential expenses are covered. Pay credit balances responsibly. Review your accounts regularly.
And remember that your credit account is not a substitute for an emergency fund. If you have to borrow money every time life surprises you, your financial system needs more protection.
Your income account should tell your money where to go. Your investment account should help you build what comes next. Your credit account should help you establish and manage borrowing responsibly. Stop looking at your entire bank balance as spending money. Once you give your money separate responsibilities, you stop simply collecting paychecks and start building a financial structure.




Comments
No comments yet, be the first submit yours below.