The Rich Call It Financial Freedom — Everybody Else Calls It Being Unable to Afford Life

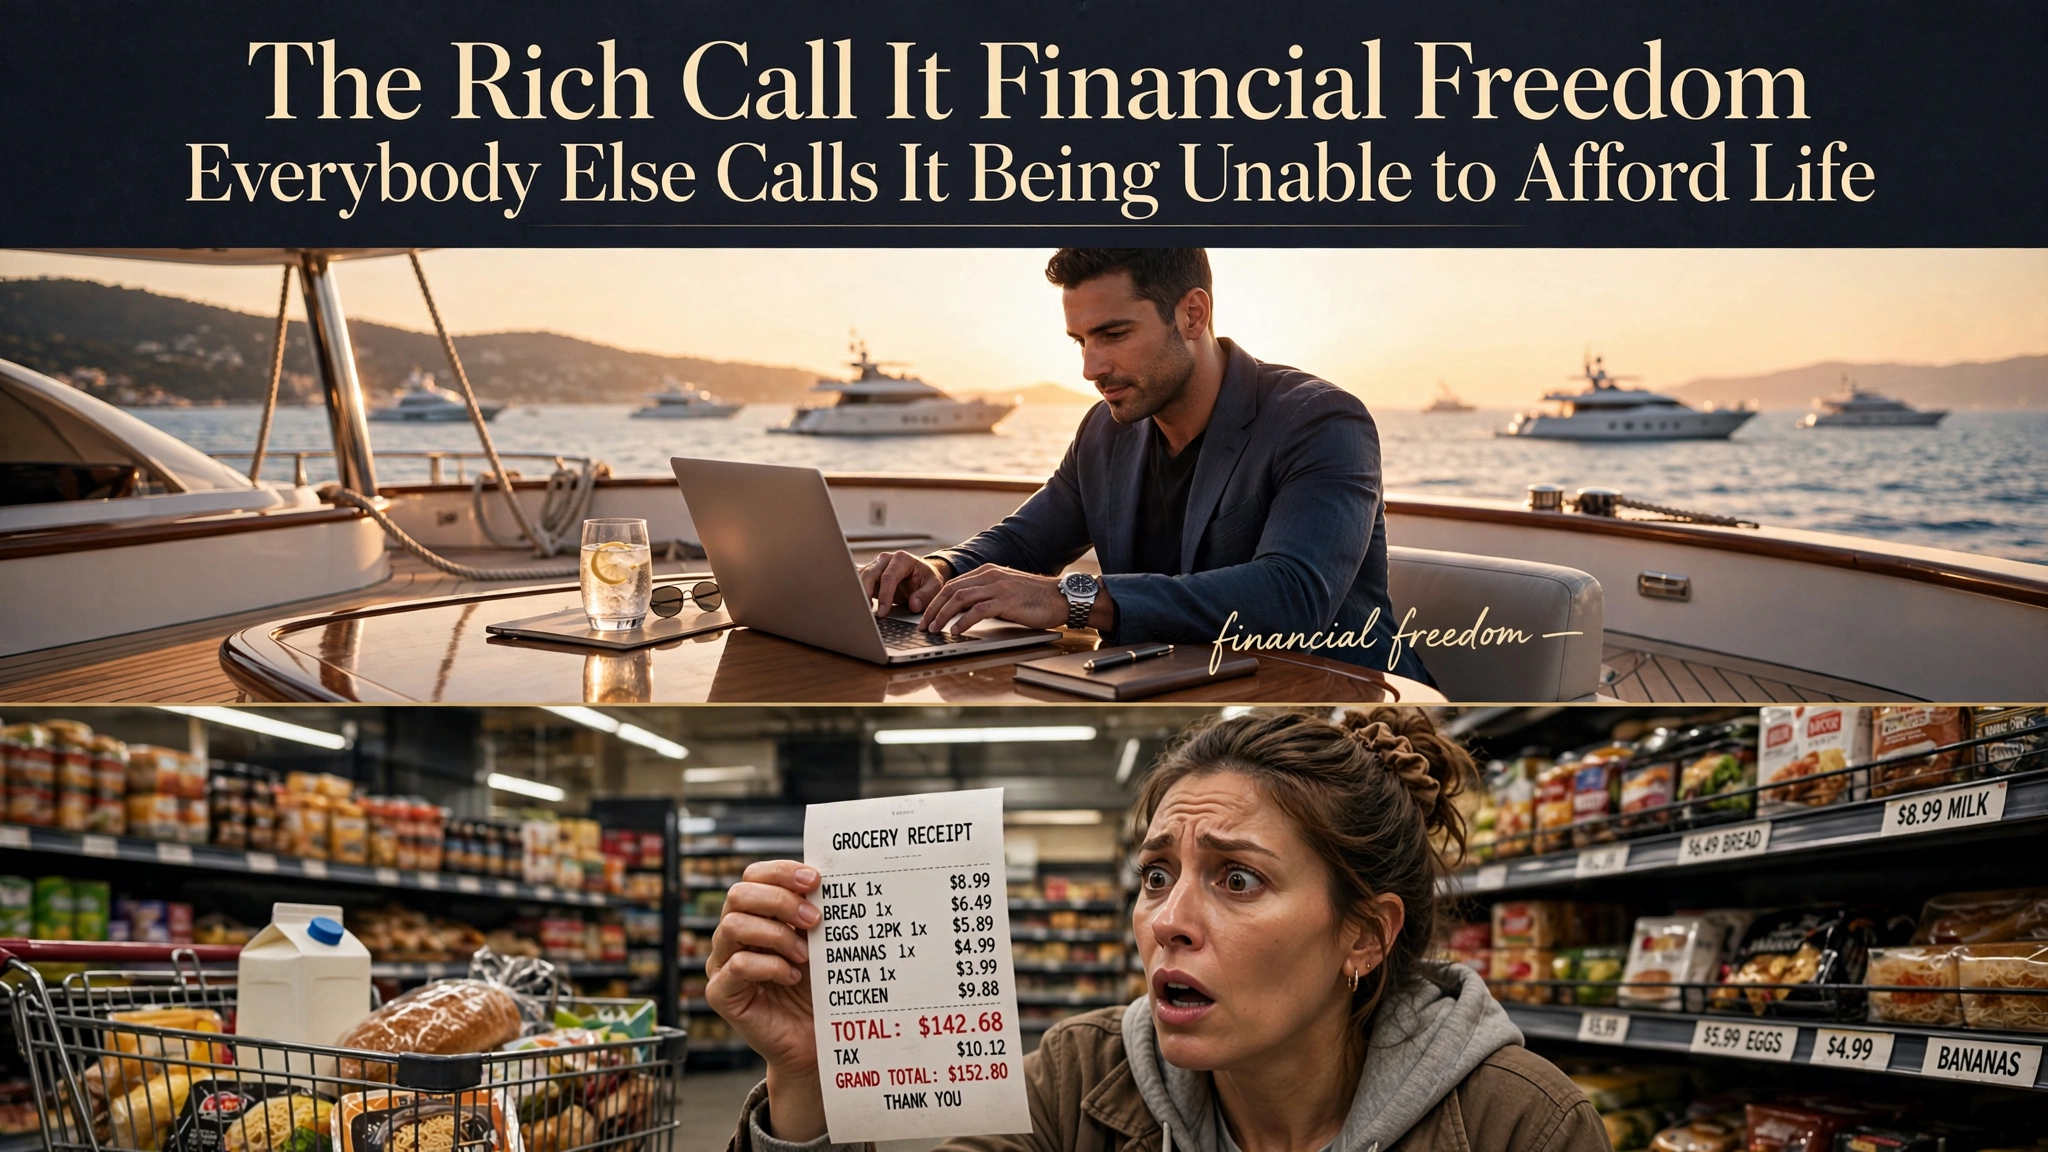
It's funny how the same economy that calls a billionaire financially successful can call a working person financially irresponsible for buying groceries with a credit card. Apparently, money problems are a character flaw when you're poor and a business strategy when you're rich.
Let's talk about one of the biggest double standards in modern society: how we judge people differently depending on how much money they have.
When a wealthy investor borrows millions of dollars to purchase assets, people call it leverage. When an ordinary person borrows money to cover rent, car repairs, or groceries, people call it living beyond their means.
When a corporation restructures its debt, it's making strategic financial decisions. When a family falls behind on its bills, people start asking what that family did wrong.
When a wealthy person uses the tax code to reduce their tax burden, they have a financial adviser. When a working person receives assistance to help feed their children, suddenly there's a debate about whether they're taking advantage of the system.
Same society. Same money. Completely different judgment.
SO IS THE PROBLEM REALLY DEBT, OR IS IT WHO GETS TO USE IT?
Debt is not automatically good or bad. A business loan can finance equipment that generates revenue. A mortgage can help someone acquire a home. A credit card can provide a useful financial buffer when managed responsibly.
But borrowing to acquire an income-producing asset is different from borrowing because your paycheck disappeared before your bills did.
The wealthy often have assets, collateral, financial advisers, and access to better borrowing terms. Someone living paycheck to paycheck may have none of those advantages. They can face higher interest rates precisely because they have less money available to protect themselves.
That's the trap: being short on money can make the money you need more expensive.
And once interest, late fees, overdrafts, and other charges start piling up, getting back to zero becomes a project of its own.
WE TELL PEOPLE TO SAVE MONEY WHILE MAKING IT EXPENSIVE TO BE ALIVE.
Save for emergencies. Save for retirement. Save for a house. Save for your children's future. Save enough to survive losing your job.
All reasonable advice.
But what happens when housing, transportation, food, insurance, utilities, and childcare consume most of your income?
You cannot save money you never have left over.
And telling somebody to stop buying coffee isn't a serious solution when their biggest expenses are rent, transportation, healthcare, and the cost of raising a family.
Yes, individual spending habits matter. Some people make financial decisions that hurt them. Personal responsibility is real. But it is equally unreasonable to assume that every struggling person is poor because they spend irresponsibly.
Some people are trying to build savings while carrying responsibilities that leave almost no room for error.
They aren't necessarily buying luxury cars or taking expensive vacations. They are trying to keep a vehicle running so they can get to work. They're replacing shoes their children outgrew. They're trying to avoid falling behind on rent because one unexpected expense can throw off an entire month.
That's not always a spending problem. Sometimes it's an income-versus-expenses problem.
AND HERE'S THE PART THAT SHOULD MAKE PEOPLE THINK.
We often measure financial success by what people can display rather than what they actually own.
A person can drive an expensive vehicle and have very little savings. Someone else can drive an older car, live modestly, and quietly build investments. One person looks wealthy; the other might have more financial security.
We celebrate the appearance of wealth because it is visible. We overlook financial stability because it often isn't.
That creates pressure to spend money proving that you're doing well instead of using that money to become more secure.
People finance lifestyles they cannot comfortably afford because they don't want to look unsuccessful. They upgrade their phones, vehicles, clothes, and living arrangements while their emergency savings remain empty.
Then they wonder why a single unexpected bill feels like a financial disaster.
The uncomfortable truth is that looking rich and becoming financially secure are two completely different goals.
THE ECONOMY DOESN'T REWARD EVERYBODY FOR WORKING HARD IN THE SAME WAY.
Working hard matters. Developing skills matters. Making thoughtful decisions matters. But the amount someone earns is also affected by their industry, location, bargaining power, access to capital, opportunities, and circumstances beyond their immediate control.
Two people can work equally hard and end up with very different financial outcomes.
One may have family support, affordable housing, and money available to invest. The other may be helping relatives, raising children, paying off old debts, or recovering from an emergency.
That doesn't mean effort is pointless. It means effort is only one part of the equation.
And when we pretend effort is the only factor, we turn every financial struggle into a moral judgment instead of examining the conditions that helped create it.
SO WHAT SHOULD FINANCIAL FREEDOM ACTUALLY MEAN?
It shouldn't just mean being able to buy whatever you want. It should mean having enough breathing room to make decisions without every choice being dictated by the next bill.
It means being able to handle a car repair without immediately reaching for a high-interest loan. It means being able to leave an unhealthy job without fearing that your family will lose its home. It means building savings without feeling guilty every time you spend money on something necessary.
For some people, financial freedom means owning a business or a portfolio of investments. For others, it means having a few thousand dollars in savings and knowing that an unexpected expense won't wipe everything out.
Those goals may look different, but the underlying principle is the same: money should provide options, not just temporary relief from financial pressure.
And that kind of security is worth pursuing even if it doesn't look impressive on social media.
THE CONTROVERSIAL QUESTION IS THIS: WHY DO WE PRAISE WEALTHY PEOPLE FOR KNOWING HOW TO WORK THE FINANCIAL SYSTEM, BUT SOMETIMES SHAME ORDINARY PEOPLE FOR STRUGGLING INSIDE IT?
We can encourage people to budget without insulting them. We can promote investing without pretending everybody starts with the same resources. We can celebrate entrepreneurship while recognizing that not everybody can afford to take the risk of leaving a steady paycheck.
And we can hold individuals accountable without acting as though financial outcomes are determined entirely by character.
Because a person's bank balance doesn't tell you everything about their intelligence, discipline, work ethic, or worth.
Sometimes the person with the smallest account is working harder than anybody realizes just to keep their life moving forward.
Sometimes the most important financial milestone isn't buying a house, purchasing a luxury vehicle, or becoming a millionaire.
Sometimes it's getting your first thousand dollars saved and finally feeling like one unexpected bill won't destroy everything you've been working toward.
That progress deserves respect, too.
Stop confusing the appearance of wealth with the reality of financial security.
The goal isn't to convince everybody you're rich. The goal is to build a life where money has less control over your decisions.
And if we're going to talk honestly about financial responsibility, let's apply that conversation consistently—whether we're discussing a struggling family, a major corporation, or a billionaire.
Because financial problems don't always mean someone failed at life. Sometimes they reveal just how expensive it has become to participate in it.



Comments
No comments yet, be the first submit yours below.